Share this publication
Send this Chervil resource to someone who may find it useful.
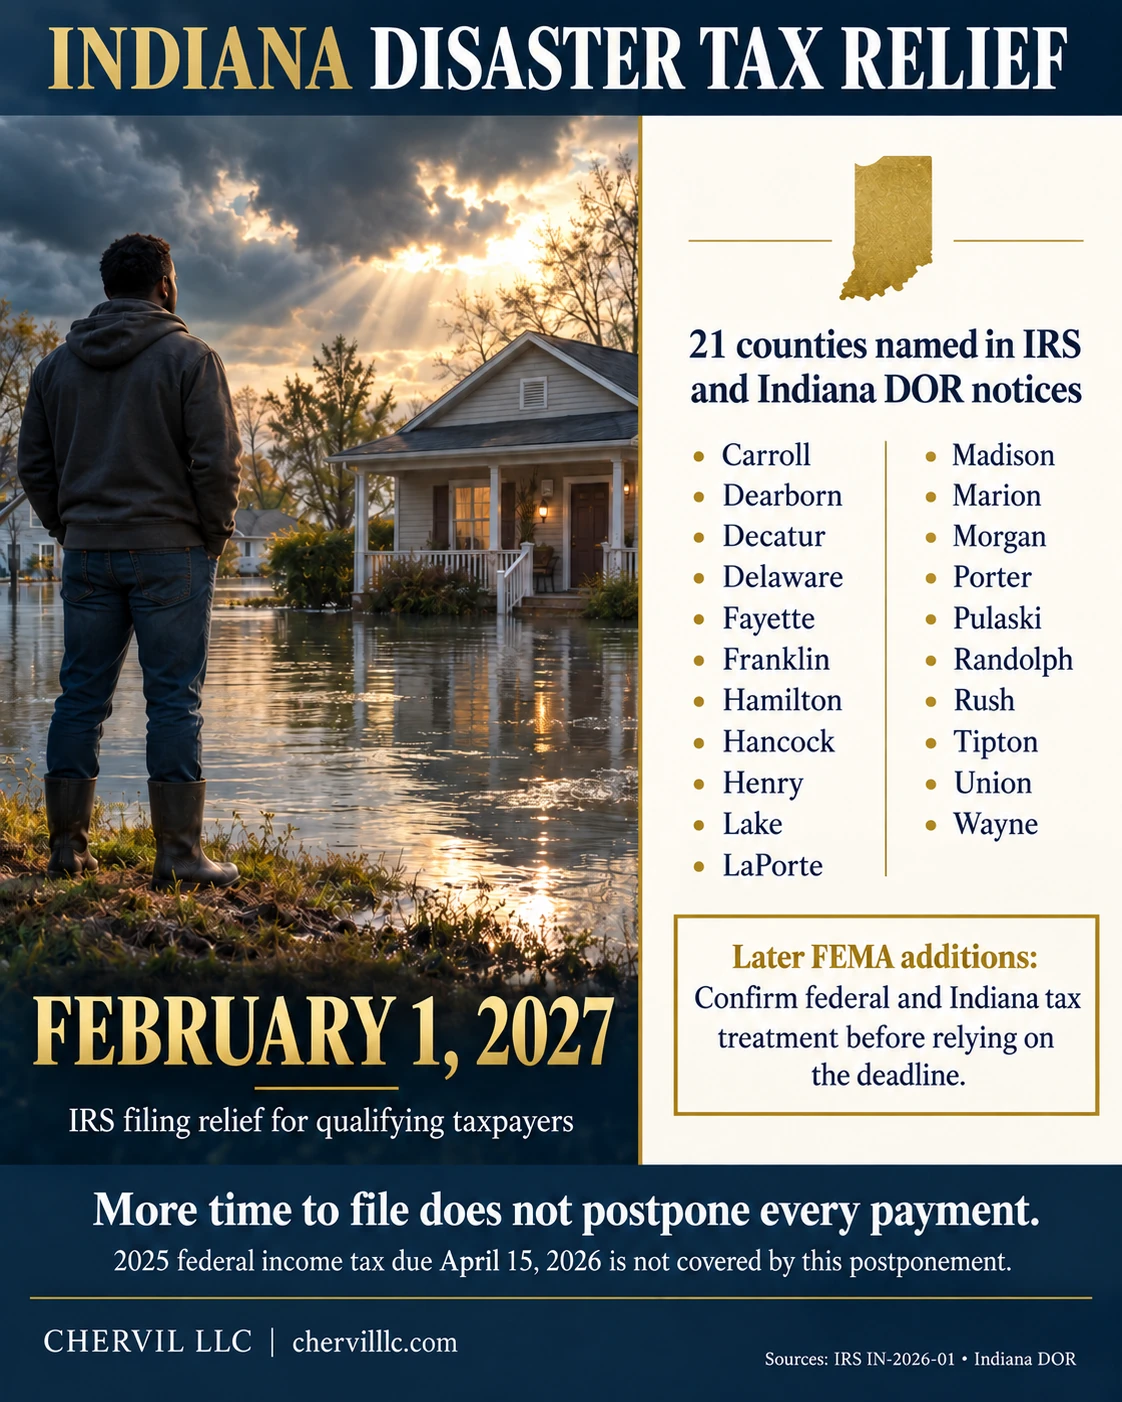
Some Indiana taxpayers with a valid extension for their 2025 federal income tax return may now file by February 1, 2027. The IRS announced targeted disaster relief following severe storms, straight-line winds, tornadoes, and flooding that began August 11, 2026. Taxpayers who do not qualify for this relief or another applicable exception still need to meet their deadlines, including the regular October 15, 2026 extended individual filing deadline. S1
The most important payment distinction is straightforward: this relief does not postpone unpaid 2025 federal individual income tax that was already due April 15, 2026. A later filing deadline does not erase an earlier payment obligation. S1, S7
Start with the county and eligibility rules
As of October 4, 2026, the IRS announcement and Indiana DOR disaster-relief table expressly name these 21 counties:
Carroll, Dearborn, Decatur, Delaware, Fayette, Franklin, Hamilton, Hancock, Henry, Lake, LaPorte, Madison, Marion, Morgan, Porter, Pulaski, Randolph, Rush, Tipton, Union, and Wayne. S1, S2
Later designations matter too. Indiana DHS identifies Cass, Pike and Putnam as additions for FEMA Individual Assistance. A subsequent congressional announcement lists Public Assistance additions that, combined with the original counties, identify nine additional counties: Cass, Fountain, Grant, Parke, Pike, Putnam, Starke, Vermillion and Warren. S3, S26
IRS policy provides federal tax relief to counties designated for Individual or Public Assistance when Individual Assistance is authorized for the disaster. That policy supports coverage of these additions. However, the IRS and DOR public tax lists reviewed on October 4 still show the original 21. If you are connected to an added county, confirm how relief applies with the IRS and separately with DOR; do not treat absence from the older list as proof of ineligibility. S6, S1, S2
For readers in central Indiana, Hamilton and Marion counties appear on both published lists. Hendricks County does not. That does not rule out another qualifying category, such as necessary records maintained in a covered area. S1, S2
Federal eligibility includes individuals whose principal residence and businesses whose principal place of business are in a covered area. This includes qualifying sole proprietors and nonprofit organizations. Merely owning property there does not establish eligibility. The residence or principal-business test does not require personal property damage or receipt of FEMA aid. S6, S8
People and businesses outside the covered area may also qualify when records needed to meet an eligible deadline are located inside it. Other categories include qualifying disaster-relief workers and certain people injured while visiting the area. These situations call for a closer review of the IRS rules and the taxpayer's circumstances. S1, S6
How federal relief is applied
The IRS generally applies relief automatically based on its address records for the covered disaster area. Eligible taxpayers outside that area, including those relying on the location of necessary records, should call the IRS disaster assistance line at 866-562-5227. A recent move or an address mismatch can also require assistance. S1, S8
Federal deadlines that may move to February 1
For qualifying taxpayers, the relief generally covers specified acts due on or after August 11, 2026, and before February 1, 2027. Both original due dates and valid extended due dates can matter. Examples include: S1, S6
- A 2025 individual income tax return with a valid extension to October 15, 2026.
- Calendar-year partnership and S corporation returns validly extended to September 15, 2026, and calendar-year C corporation returns validly extended to October 15. S9, S14, S15
- Calendar-year Forms 990, 990-EZ and 990-PF validly extended to November 16, 2026. This example does not apply to Form 990-N. S10
- Individual estimated income tax payments due September 15, 2026, and January 15, 2027. Corporate estimates can also qualify when their due dates fall within the covered period.
- Quarterly payroll and certain excise tax returns normally due November 2, 2026. This is a return-filing rule; deposits are addressed separately below. S1, S15
What the postponement does not change
Unpaid 2025 federal individual income tax originally due April 15, 2026 remains outside this disaster postponement. Interest and any applicable late-payment penalties can continue on that balance. An ordinary extension grants additional time to file; it generally does not grant additional time to pay. S1, S7, S8
For example, a qualifying individual could have until February 1 to submit an extended 2025 return while still owing interest on tax that should have been paid in April. By comparison, a qualifying September 2026 estimated payment falls within the disaster period and may receive a postponed payment deadline. Keeping those obligations on separate lines of a tax calendar helps avoid treating them as one bill.
Payroll and excise tax deposits have a narrower rule than payroll and excise tax returns. Deposit deadlines were not broadly moved to February 1. The IRS provided deposit-penalty relief for deposits due August 11 through August 25, 2026, only if the deposits were made by August 26. That catch-up date has passed. S1
Information returns such as the W-2 and 1099 series generally are excluded unless a specifically covered act applies. Check the precise form before delaying it. The announcement also says existing payment-plan direct debits continue, with usual interest and late-payment charges; do not assume withdrawals will stop. S1
Indiana relief needs its own review
Indiana DOR separately lists February 1, 2027 relief for specified Indiana returns and estimated payments in its covered counties. Its table includes individual IT-40 and fiduciary returns; nonprofit IT-20NP returns; IT-20S and IT-65 returns; and FIT and IT-20 returns. The state table uses October or November filing dates depending on return type, so it should not be read as a copy of the federal calendar. S2
For individual estimated payments, DOR lists September 15, 2026 and January 15, 2027 installments. For IT-6 and IT-6WTH, it lists September and December 2026 installments. Eligible listed obligations move to February 1, 2027. DOR places the Indiana relief under its automatic, no-action-required category. S2
The announcement does not support a blanket statement that every Indiana tax or an unpaid balance from before the disaster receives a new deadline. Indiana also has separate interest and penalty rules. Check the exact form, payment period, and relief provision before delaying payment or assuming earlier charges will disappear. If eligible relief was not applied, DOR directs taxpayers to its Taxpayer Advocate Office at 317-232-4692. S2, S12
A practical checklist for the next filing step
- Confirm the relevant county and eligibility category. Check the latest IRS and DOR notices, especially for a later FEMA addition.
- List each return and payment by agency, tax year, form, original deadline, and any valid extension. Mark the obligations that qualify for postponement.
- Separate old balances from newly postponed payments. Ask what interest or penalties may continue before deciding when to pay.
- Preserve extension confirmations, payment receipts, relevant address and records-location evidence, and disaster-related correspondence.
- Coordinate with your preparer, bookkeeper, and payroll provider. Make sure everyone is using the correct dates for the obligations they handle.
- Set a completion plan before February 1, 2027. Extra time can help with missing records, but waiting until the final day leaves less room to correct a rejected filing.
If an incorrect penalty notice arrives
Do not ignore the notice. Compare the tax period and original due date with your eligibility and the disaster window. For a federal late-filing or late-payment penalty that should be covered, call the number printed on the IRS notice and request the disaster-related correction. Keep the notice and a record of the response. An Indiana notice requires a separate DOR review. S1, S2
Getting help with your deadlines
The right deadline depends on your location, eligibility, return, and payment history. If you believe you or your business may qualify for the Indiana disaster-related tax postponement, Chervil LLC can help you review the applicable deadlines and determine the next filing step.
This publication provides general educational information. Eligibility and tax treatment depend on your circumstances and current official guidance. It is not individualized tax or legal advice.
Official guidance
S1 IRS Indiana disaster announcement
S2 Indiana DOR disaster relief
S3 Indiana DHS August 2026 disaster
S6 IRS disaster program guidelines sections 25.16.1.3 and 25.16.1.4.2
S10 IRS exempt organization return due dates
S12 Indiana DOR extensions to file
S14 IRS third quarter tax calendar
CONNECT WITH CHERVIL LLC
Need help reviewing your tax deadlines?
Chervil LLC can help you review the applicable deadlines and determine the next filing step.